Fog City SF Knob and Tube arranges electrical inspections for insurance in San Francisco and the East Bay: every circuit is tested, and the findings on knob and tube, the panel and circuit protection are written up to answer what your insurer or broker asked. Licensed and insured electrical contractors (California C-10) do the testing and write the findings. They write as electrical contractors, not as home inspectors or engineers, and no inspection can promise that a carrier will write or renew a policy.
This page is about the insurer’s question. The broader knob and tube inspection is the scope-finding evaluation that maps a house before you decide what to do with it. The testing is the same; what differs is the reader, the questions the written findings answer, and what usually happens next.
Why insurers ask about the wiring
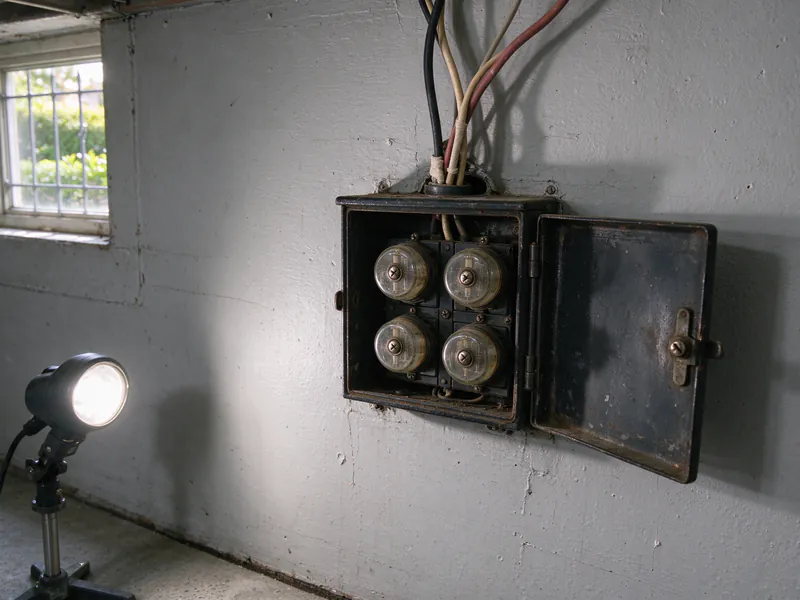
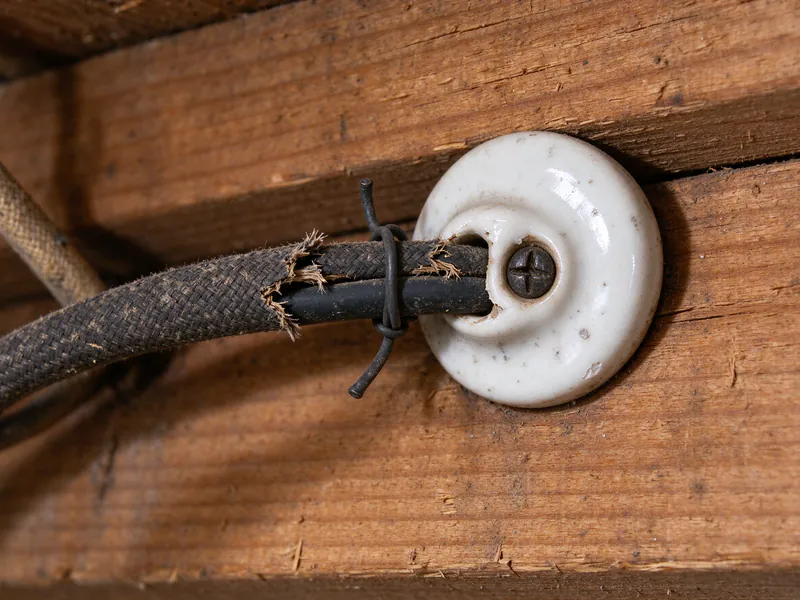
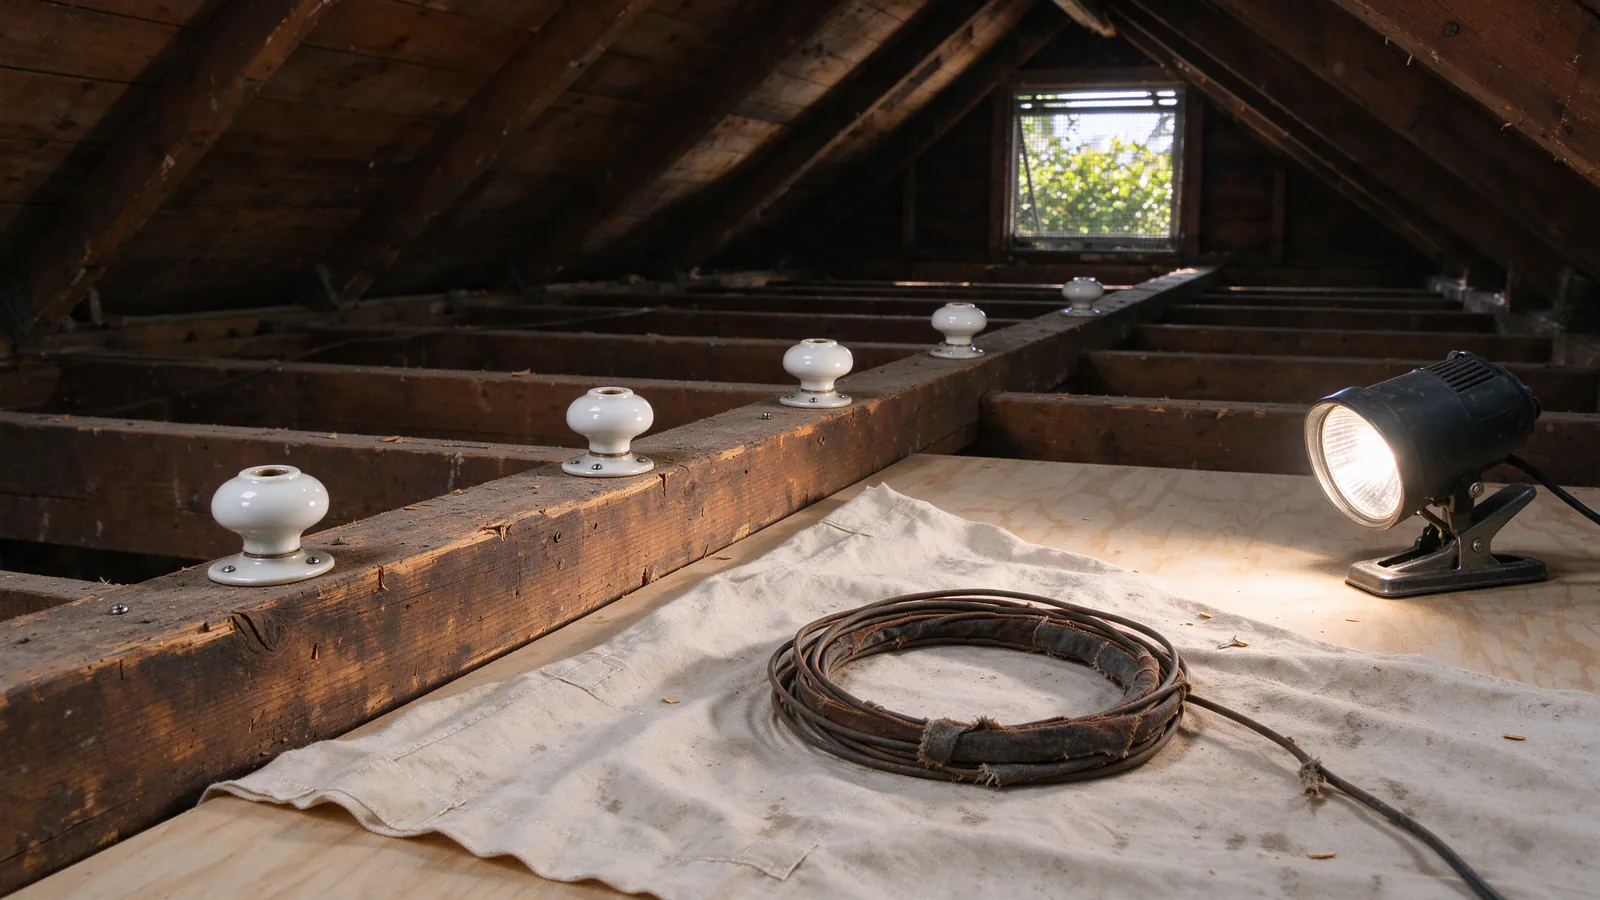
Underwriters ask about knob and tube because it is old, ungrounded, often altered by later work and hard to see. A Bay Area broker told ABC7 News that if knob and tube goes on an application, “we are going to get declined.” The City of Berkeley states in its energy ordinance materials that many insurance providers will not issue or renew homeowner policies for houses with active knob and tube wiring. The same ABC7 report quoted San Francisco Fire Department investigators saying the department has not seen trends in knob and tube residential fires, which is why the useful question is what is live in a particular house, not how old it is.
San Francisco’s own permit records show insurance driving work. Of 2,023 DBI electrical permits filed from January 2016 to October 2026 whose descriptions name knob and tube, 30 cite an insurer, with wording such as “knob and tube wiring removal for insurance purposes.” California FAIR Plan residential policies across San Francisco ZIP codes rose from 335 in September 2021 to 1,861 in September 2025. The FAIR Plan publishes no reasons by policy, so that rise covers every cause, not only wiring.
What happens on the first visit
The visit starts with the insurer’s letter or form, if there is one. Carriers word their questions differently: one asks whether any knob and tube is present, another whether it is active, another wants the panel type or a plan to replace it. Reading that first means the testing answers the question that was asked.
Then every circuit is tested and traced from the panel or fuse box, and each one is recorded as active knob and tube, disconnected knob and tube, later wiring, or a mix of the two. The panel or fuse box is recorded as found, with the size of each fuse or breaker against the wire it protects. The attic, basement, crawlspace and garage are walked to note visible condition, splices, junction boxes and any insulation lying over live runs. Nothing is disturbed to get a better look.
What underwriters ask, and what homeowners report
The California Department of Insurance’s consumer guides do not address knob and tube, and carriers set and change their own underwriting rules, so the questions vary. Homeowners report a few that recur. Is any knob and tube present, and is it active? How many circuits, and in which rooms? Has it been altered, or is it “unmolested,” in one Oakland owner’s words? What kind of panel is there? Is replacement planned, and by when? Homeowners also report carriers offering a policy on condition that the wiring be replaced within a short window, around 60 days in one account, and others that would not insure any knob and tube at all.
Two habits make the inspection more useful. Answer only what was asked, and answer it exactly; an overstated “no knob and tube” can cause more trouble later than an accurate “two circuits remain active.” And keep the full findings even if the carrier wants only a one-line answer, because the next carrier, a buyer or a lender may ask a different question.
What written findings can and cannot state
Written findings can state which circuits were tested and what each runs on, which knob and tube is active and which is disconnected, the panel and protection found, and the condition of what could be seen. They can describe a disconnected run as disconnected at both ends when that was verified. They can say which spaces could not be reached.
They cannot certify concealed wiring nobody could see, declare a house safe, or speak for the carrier. They are not a home inspection, an engineering report or a permit inspection. If a form asks for a statement that testing cannot support, the right answer is to say so rather than sign it. The California insurance guide explains how carriers, brokers and the FAIR Plan fit together.
Need findings an underwriter can read?
Every circuit is tested and recorded as active, disconnected or mixed, with the panel and protection noted as found.
When the answer is work, the permit final is the proof
Often the findings lead to work. Live knob and tube may be replaced through partial replacement or whole-house rewiring; dead runs may be disconnected and taken out through knob and tube removal. Either way, the strongest document for an insurer afterwards is not a letter but the paper trail of permitted work.
That trail has three parts. DBI’s electrical permit names the scope, the pre-cover and final inspections show the city inspected it, and the Certificate to Connect Current, the Green Tag, follows the final. The written circuit record and labeled panel directory then show circuit by circuit what was replaced. After a partial job, the record must also say exactly what knob and tube remains, because a carrier that later finds an old circuit nobody mentioned will treat the whole file differently.
The three certifications people mean
“Knob and tube certification” means different documents to different people, and the comparison table further down sets them side by side. An insurer’s letter describes findings. The California Electrical Code’s insulation exception is narrower: insulation may envelop concealed knob and tube only where a California-licensed electrical contractor surveys the wiring and certifies it is in good condition, without deterioration, improper overcurrent protection, or improper connections or splices, and the certification is filed with the building department with a copy to the owner. No San Francisco DBI form for that certification was found; Berkeley has its own, Form #146, covered on the Berkeley page. The third is BayREN’s EASE Home certification that knob and tube is inactive, for which BayREN announced a $300 rebate for eligible households (confirm with BayREN that it is still offered), described on the removal page and in the BayREN rebate guide.
Deadlines, the FAIR Plan and a sale
The California Department of Insurance says that after a policy’s first 60 days an insurer may cancel only for reasons the law sets, and that a non-renewal needs written notice at least 75 days before the policy ends, with the reason stated. That window is the practical deadline for testing, and for permitted work if the findings call for it. The FAIR Plan describes itself as the insurer of last resort when no other option is reasonably available, after a broker’s diligent search of the regular market, and its policies cover basic fire, with Difference in Conditions policies from other insurers filling gaps. The non-renewal article walks through the sequence.
On a sale, the wiring question moves to the buyer. A San Francisco agent told the Chronicle that insurance is now often a contingency of the purchase, and another told ABC7 that without insurance the lender will not approve the mortgage. Sellers who test first can disclose accurately, and buyers can book an inspection during their contingency period; the buying guide and selling guide cover each side.